Mobile Home Insurance for Tampa FL
Specialized Florida mobile home coverage for dwelling, belongings, liability and wind, compared across multiple Florida-licensed carriers.
Florida mobile homes need their own kind of policy
Mobile home insurance is not a standard homeowners policy. Factory-built homes are transported, anchored and exposed to Florida weather differently, and many carriers use separate rules and forms for them.
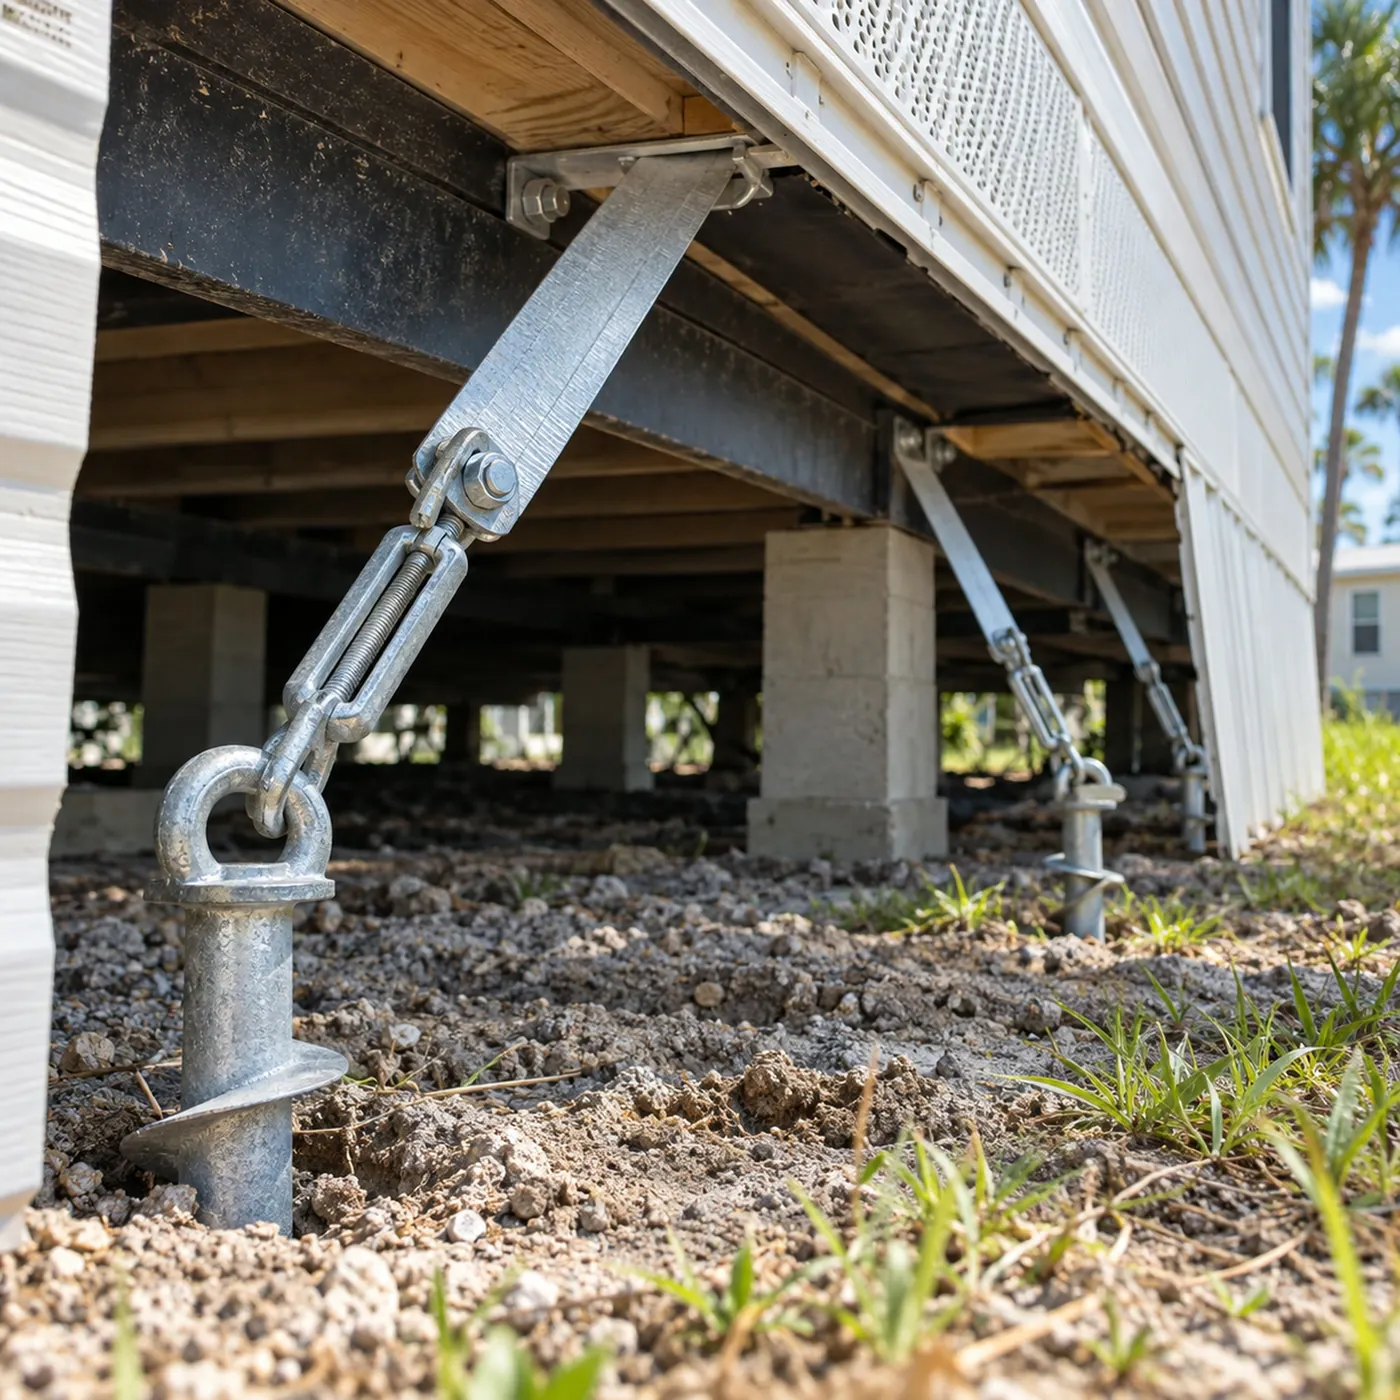
- Hurricane wind loads and tie-down systems
- Older roof structures, skirting and additions
- Flood exposure across Florida
- What is inside the policy matters most
What mobile homes can we insure?
If your home meets these general criteria, there is a strong chance we can find you coverage with a Florida-licensed carrier partner.
What a Florida mobile home policy covers
A typical policy protects four main areas, plus wind and attached structures. We review each section with you so limits are set correctly.
Dwelling coverage
Walls, roof, floors and built-in appliances. Set this limit at true replacement cost.
Personal belongings
Furniture, electronics and clothing. Replacement cost is strongly recommended over ACV.
Liability protection
Legal fees and damages if someone is hurt. Standard limits often start at $100,000.
Additional living expenses
Hotel, meals and temporary housing if a covered loss makes your home uninhabitable.
Wind and hurricane
Part of the standard policy in most Florida counties. Hurricane deductibles vary by carrier.
Attached structures
Carports, screen rooms and porches may need to be listed separately with their own limits.
What to check before picking a policy
The cheapest quote is not always the best one. Review these points when comparing mobile home insurance options side by side.
- Policy type: a DP-1 covers named perils only, an MH-O3 covers open perils
- Dwelling limit: what it costs to rebuild today, not what you paid years ago
- Replacement cost vs. actual cash value, which deducts depreciation
- Wind coverage: it may be excluded in some southern coastal areas or older homes
- Attached structures: carports, screen rooms and porches may need listing
Compare hurricane deductibles, not just premiums
Some carriers charge 2% or 5% of dwelling value, others a flat $1,000. On a $120,000 home, that is $6,000 versus $1,000 out of pocket after a hurricane.
Why Tampa Bay families choose FishHawk
Independently owned for 30 years. We compare coverage and pricing across multiple Florida-licensed carriers, and our loyalty is to you, not any single insurer.
- Independent broker: never a single take-it-or-leave-it offer
- Based in Valrico, serving Hillsborough County and all of Florida
- Real people answer at 813-776-1542, questions answered same day
- Annual policy reviews and shopping when better options appear
Covered in 3 simple steps
Tell us about your home
Call 813-776-1542 or fill out the form. A few quick questions about your property and needs.
We shop multiple carriers
An agent compares rates and coverage from multiple Florida-licensed carriers on your behalf.
Choose your policy
Pick what fits your needs and budget. We bind coverage, typically the same business day.
- 30Years of experience, independently owned
- 30Years serving Hillsborough County and Florida
- 1977Well-maintained homes back to this year can be covered
- 3 minAbout how long a free quote request takes
Frequently asked questions
What is mobile home insurance in Florida?
Mobile home insurance is a specialized property insurance policy designed for factory-built homes in Florida. It covers the dwelling structure, your personal belongings, liability protection, and additional living expenses if a covered loss makes your home temporarily uninhabitable. Unlike a standard homeowners policy, mobile home insurance is built around how factory-constructed homes handle wind, storms, and Florida weather.
How much does mobile home insurance cost in Florida?
Most Florida mobile home owners pay between $800 and $3,200 per year. Your premium depends on your home's age and size, your county (coastal areas cost more), whether wind coverage is included, your coverage limits and deductibles, and your claims history. FishHawk Insurance Center compares multiple FL-licensed carriers simultaneously to find the most competitive rate for your specific home.
Does mobile home insurance cover hurricanes?
Yes, FishHawk Insurance Center writes mobile home policies with wind and hurricane coverage across Florida. In most counties, wind is part of the standard policy. In some southern coastal areas, options may be more limited. Hurricane deductibles vary significantly between carriers, some charge a percentage of dwelling value (2%-5%), others offer a flat dollar amount like $1,000. On a $120,000 home, that's the difference between a $6,000 and a $1,000 deductible.
Does flood insurance come with my mobile home policy?
No, standard mobile home insurance policies do not cover flood damage. A separate flood policy is required. FishHawk Insurance Center quotes flood coverage alongside your home policy so you see the complete picture. Given Florida's hurricane exposure and tropical rainfall, flood coverage is strongly recommended for every mobile home owner in the state.
Can older mobile homes built before 1994 get insurance in Florida?
Yes. FishHawk Insurance Center works with carriers that can often insure well-maintained mobile homes built as far back as 1977, although carrier options and coverage terms become more limited as homes age. Homes built in 1994 and newer typically qualify for broader coverage because HUD strengthened wind resistance standards that year after Hurricane Andrew. Updated roofs, electrical systems, and proper tie-downs help older homes qualify for better options.
What should I look for when comparing mobile home insurance quotes?
Price is only part of the picture. Check whether the policy is a DP-1 (named perils only) or MH-03 (open perils, much broader coverage). Confirm the dwelling coverage amount reflects actual replacement cost. Ask whether the home is insured at replacement cost or actual cash value, this can mean tens of thousands of dollars difference after a claim. Verify that wind coverage is included. Check the hurricane deductible structure. And confirm how attached structures like carports and screen rooms are covered.