Home Insurance for Tampa FL
Florida homeowners insurance for Tampa Bay, compared across multiple Florida-licensed carriers, with wind mitigation and 4-point discounts reviewed.
What every Tampa Bay homeowner needs to know
Florida is a high-catastrophe market. Premiums are rising, carriers are exiting, and coverage gaps often show up at claim time. Your wind zone, flood zone, home age and construction all shape your options.
- Exposed to hurricane and tropical storm damage
- Risk varies block by block across Hillsborough County
- Home age and construction type change your premium
- Multiple Florida-licensed carriers compared for 30 years
What your Florida home insurance policy covers
A standard HO-3 policy has six sections. Set each limit correctly so you are not underinsured when a claim happens.
Coverage A: Dwelling
Walls, roof, floors and built-in appliances. Insure at replacement cost, where most major claims are paid.
Coverage B: Other Structures
Fences, sheds, detached garages and guest houses. Typically set at 10% of your Coverage A limit.
Coverage C: Personal Property
Your belongings, paid at actual cash value or replacement cost. Replacement cost is strongly recommended.
Coverage D: Loss of Use
Hotel, meals and temporary rental while repairs are made. Most policies set this at 20-30% of Coverage A.
Coverage E: Personal Liability
Legal fees and damages if someone is hurt on your property. The standard $100,000 limit is often not enough.
Coverage F: Medical Payments
Minor medical bills for injured guests regardless of fault, typically $1,000-$5,000 per claim.
Wind mitigation and 4-point inspection discounts
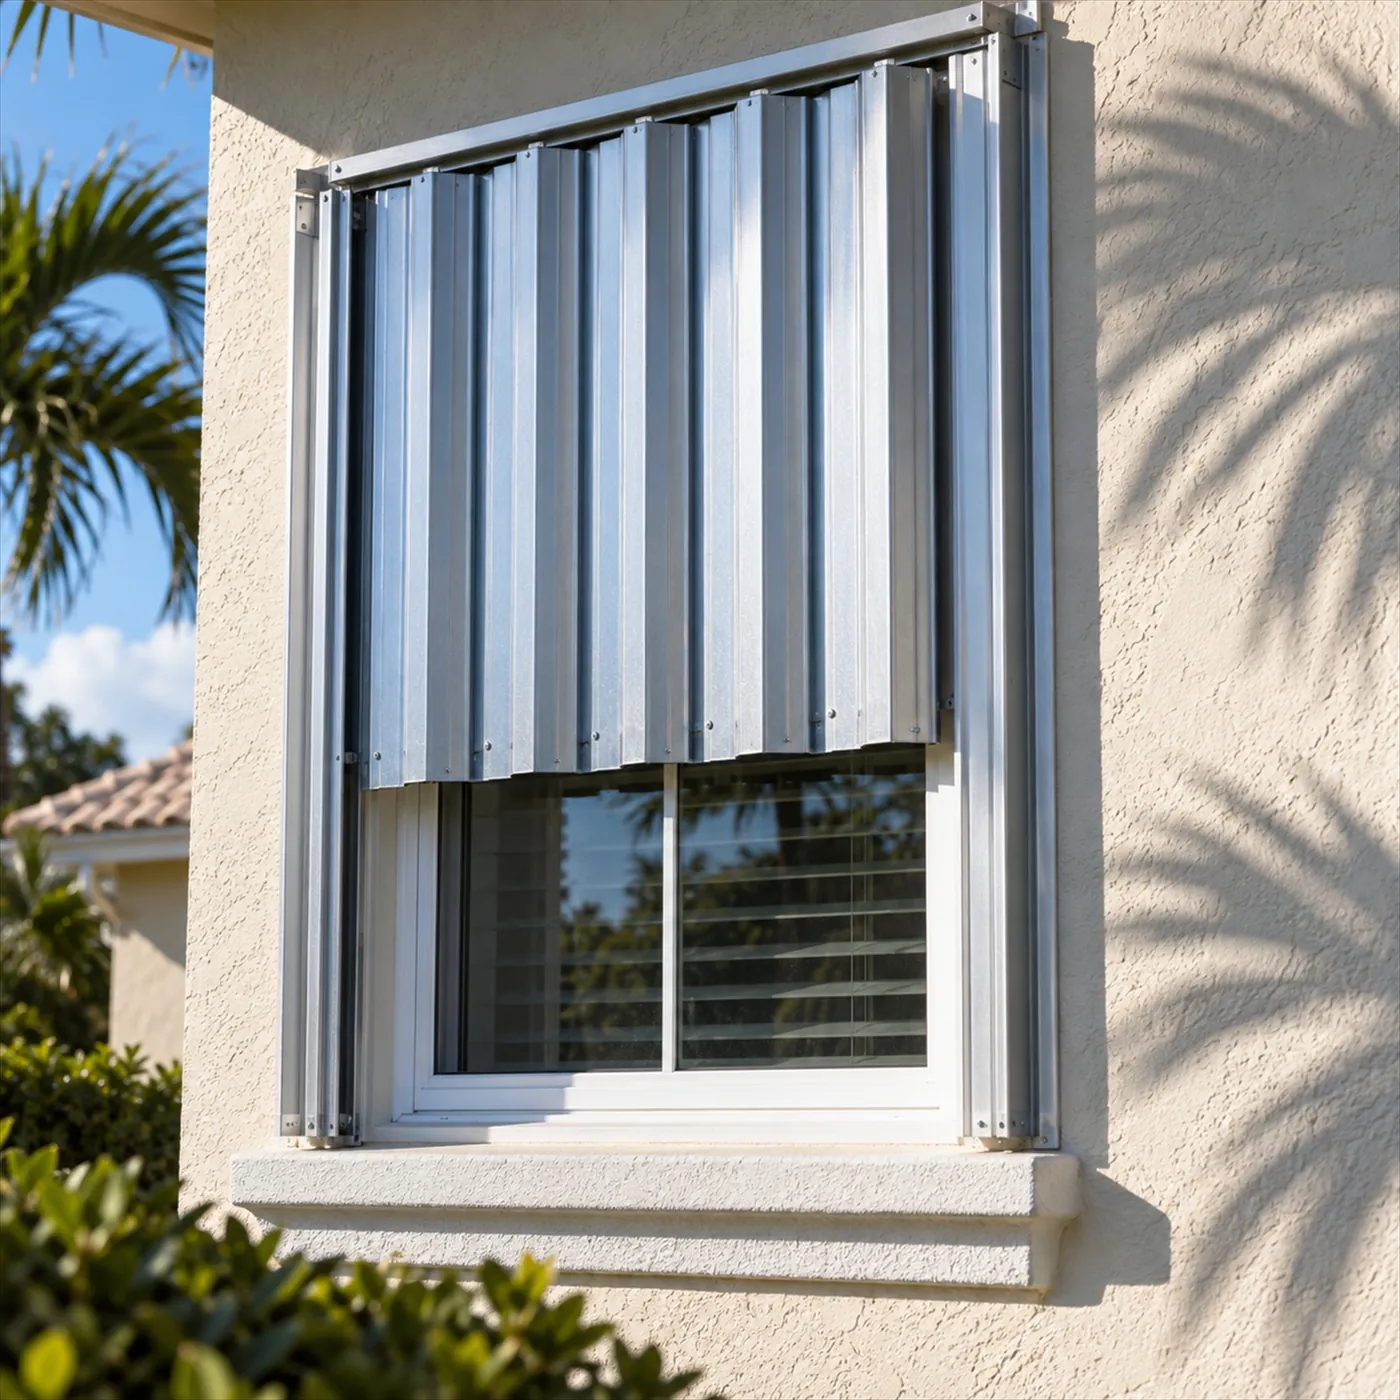
Two inspections can save Tampa Bay homeowners hundreds, sometimes thousands, of dollars a year. We review every available discount when building your quote.
- Wind mitigation: the biggest discount available in Florida homeowners insurance
- Hip roofs, hurricane clips and impact windows or shutters can cut premiums
- 4-point: roof, electrical, plumbing and HVAC reviewed for eligibility and pricing
- Many carriers require a 4-point inspection on homes 15+ years old
- We can connect you with licensed inspectors
Florida homeowners policy forms
The right form depends on your property type. We help you pick the correct form and carrier for your home.
HO-3: Most Common
The standard single-family form, with open perils on the dwelling. Required by most mortgage lenders.
HO-6: Condo Owners
Interior unit, belongings and liability. Works alongside your condo association master policy.
HO-4: Renters
A renter's belongings and liability, not the building. One of the most affordable coverages in Florida.
HO-5: Comprehensive
Open perils on both dwelling and belongings. The broadest coverage, generally at a higher premium.
HO-7: Mobile or Manufactured
Built for mobile and manufactured homes, which standard HO-3 policies typically exclude.
DP-3: Dwelling Fire
For rental and investment homes. Covers the structure and landlord property, not tenant belongings.
Most Tampa Bay clients are covered the same business day they contact us
A quote takes about 3 minutes. We shop multiple Florida-licensed carriers and never sell your data. Call 813-776-1542.
- 30Years placing Florida homeowners insurance
- 30Years serving Hillsborough County families
- 6Coverage sections in a standard HO-3 policy
- 15+Home age in years when many carriers require a 4-point
Why Tampa Bay families choose FishHawk
Independently owned and operating in Florida for 30 years. We are not captive to any single carrier, so our loyalty is entirely to you.
- Independent broker: multiple FL-licensed carriers compared at once
- Based in Valrico, serving Hillsborough County families for 30 years
- Same-day answers and a real person at 813-776-1542
- Annual reviews, shopping competing carriers when better rates appear
Getting covered in 3 simple steps
Tell us about your situation
Call 813-776-1542 or fill out the form. We ask only what we need for an accurate quote.
We shop multiple carriers
An agent compares rates and coverage from multiple Florida-licensed carriers on your behalf.
Choose your policy and get covered
Pick the policy that fits your budget. We bind coverage, typically the same business day.
Frequently asked questions
Does Florida home insurance cover hurricane damage?
Yes, wind damage from hurricanes is covered under a standard Florida HO-3 policy, though your policy may have a separate hurricane deductible. However, your home insurance does NOT cover flood damage, that requires a separate flood insurance policy.
What is a wind mitigation inspection and how much can I save?
A wind mitigation inspection documents your home's wind-resistant features. Homes with hip roofs, hurricane clips, and impact windows can save 20%-60% or more on the wind portion of their premium.
Why is my Florida homeowners insurance so expensive?
Florida is a high-catastrophe state, hurricane risk, litigation patterns, and the cost of reinsurance all drive premiums higher than most states. FishHawk Insurance Center shops multiple carriers to find the most competitive rate for your specific home.
Is flood insurance required for my Tampa Bay home?
If your home is in a FEMA Special Flood Hazard Area, your mortgage lender requires flood insurance. FishHawk Insurance Center recommends flood coverage for all Tampa Bay homeowners.
What is a 4-point inspection and when do I need one?
A 4-point inspection reviews your home's four major systems, roof, electrical, plumbing, and HVAC. Most Florida carriers require it for homes 15+ years old.